

12th October 2026
By Shubhii Verma
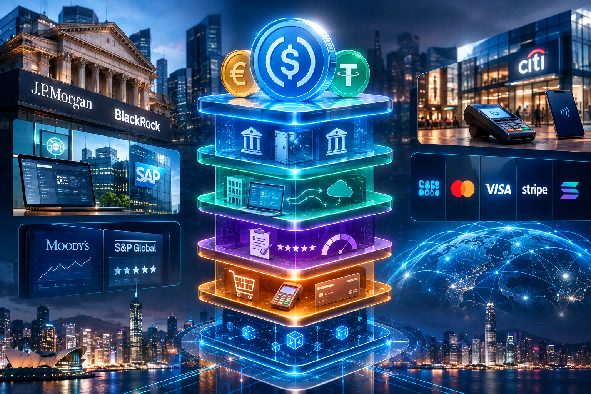
Institutional stablecoin infrastructure saw developments across reserves, enterprise payments, credit ratings, merchant networks and settlement systems between October 6 and 8, 2026. Together, these initiatives indicate growing efforts to integrate blockchain-based money into conventional financial operations, although widespread adoption remains uncertain.
Reserve Infrastructure
JPMorgan’s JLTXX fund and BlackRock’s BSTBL ecosystem feature prominently in the institutional reserve landscape. The original report cites $733.7 million in assets under management for JLTXX and a $6.1 billion parent fund supporting BSTBL. These figures highlight the growing role of tokenized funds in providing reserve-management options, though claims about mandatory dual-reserve strategies require independent legal verification.
Enterprise Payments
SAP’s integration of stablecoin payment capabilities into enterprise software represents another development. The report describes support for USDC and EURC across 89 payment corridors, potentially reaching approximately 400,000 customers. Embedding digital payments into corporate resource-planning systems could reduce friction between accounting workflows and blockchain settlement.
Credit Assessment
Credit ratings are also entering the stablecoin ecosystem. The report references Moody’s B3 rating for Sky Protocol and an S&P B- rating, suggesting that institutional risk assessment is becoming more structured. However, ratings evaluate specific risks and should not be interpreted as guarantees of repayment, liquidity or stability.
Merchant Networks
Citi’s reported connection between its payment network and Coinbase stablecoin infrastructure could expand merchant access to blockchain-based settlement. With a network processing trillions of dollars annually, such integration could make stablecoin payments more accessible. Actual adoption will depend on merchant incentives, transaction costs, regulatory requirements and consumer demand.
Settlement Rails
The report identifies four settlement developments involving SoFi and Mastercard, Visa, Stripe and Solana. These initiatives illustrate different approaches to connecting digital assets with payment networks and programmable settlement. Their commercial significance will depend on transaction volumes, reliability, interoperability and sustained customer usage.
The developments are unfolding ahead of the reported January 18, 2027, effective date of the GENIUS Act. The article also highlights delayed federal rulemaking, creating uncertainty over how implementation requirements will apply across the industry.
Community banks face additional pressure. A survey attributed to the American Bankers Association and Conference of State Bank Supervisors reportedly found that 18% of surveyed institutions planned tokenized-deposit launches within twelve months, while 60% anticipated competitive disadvantages from stablecoin payment networks.
Blockwind News ANALYSIS
The emerging stablecoin ecosystem represents a race to build the financial infrastructure required for institutional adoption, rather than a completed transformation of global finance. Reserve management, enterprise software, credit assessments, merchant networks and settlement systems must operate seamlessly before stablecoins can become mainstream payment instruments.
The real test is whether these technologies deliver tangible advantages over traditional financial rails. Faster transactions mean little if liquidity remains fragmented, operational costs stay high or consumer protections weaken.
Regulatory clarity will also shape the sector’s trajectory, particularly as institutions navigate evolving compliance requirements. Interoperability between banks, blockchain networks and payment providers will be equally critical.
Ultimately, stablecoins must prove their commercial value through reliability, transparency and sustained usage. Infrastructure may be advancing rapidly, but adoption will determine its lasting significance.
