

22nd September 2026
By Anjali Kochhar
Singapore’s cryptocurrency landscape is experiencing an unprecedented structural transformation. Driven by institutional validation, widespread retail adoption, and the ubiquity of instant digital payment ecosystems like PayNow, digital payment tokens have solidified their presence in the city-state’s mainstream financial system. This rapid adoption has prompted the Monetary Authority of Singapore (MAS) to enforce a series of rigorous regulatory updates designed to insulate retail investors from market volatility while cementing the nation’s position as a highly transparent digital asset hub.
Local fiat-to-crypto gateways have reported record-breaking transaction volumes, fueled primarily by the friction-free integration of instant settlement networks. “The ability to instantly convert Singapore Dollars (SGD) into core digital assets like Ethereum (ETH) via PayNow has radically lowered the barrier to entry,” notes a senior market analyst at a prominent local brokerage. “What used to require multi-day bank transfers can now be executed within 60 seconds through a standard mobile banking app. This convenience has drawn an entirely new demographic of casual, retail participants into the ecosystem.”
The Allure of Instant Settlement
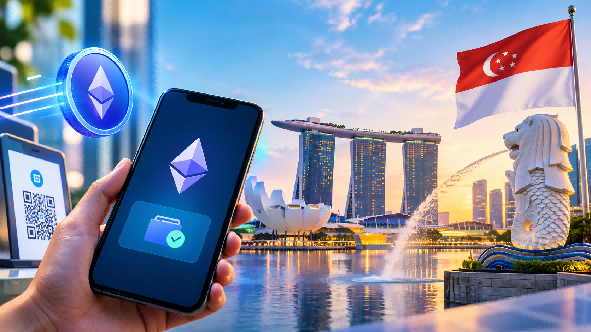
The explosive growth in trading activity is tightly linked to the integration of local payment infrastructure with MAS-licensed entities. Homegrown firms like Coinhako, alongside international heavyweights operating under Major Payment Institution (MPI) licenses such as OKX Singapore, Independent Reserve, and Coinbase, have embedded Singpass identification and PayNow settlement directly into their user interfaces.
For the average Singaporean investor, the process has mutated into a routine e-commerce transaction. By scanning a dynamically generated QR code through banking applications like DBS digibank, OCBC Digital, or UOB TMRW, capital is transferred into digital wallets with unprecedented speed.
Furthermore, Singapore’s highly favorable fiscal policies continue to serve as a massive magnet for capital. Under current tax frameworks, individual investors enjoy a 0% capital gains tax on digital asset profits. This regulatory arbitrage, combined with a highly automated infrastructure, has turned the local market into an incubation ground for high-frequency retail trading and long-term asset accumulation alike.
Regulatory Interventions: Consumer Protection First
However, this rapid retail expansion has forced the central bank to intervene with consumer protection measures. Recognizing that retail enthusiasm often outpaces risk awareness, MAS has systematically rolled out stringent compliance directives for MPI license holders.
Among the most significant measures are strict consumer access restrictions. Licensed crypto platforms are now legally prohibited from offering incentives, such as free tokens or shopping vouchers, to entice retail credit card spending on digital currencies. Additionally, exchanges are barred from offering margin trading or leverage to retail customers, a move intended to prevent catastrophic liquidations during sudden market downturns.
“MAS’s stance is explicit: digital asset speculation is inherently high-risk and unsuitable for the general public,” says a compliance consultant specializing in FinTech regulations. “The regulatory goal isn’t to choke off innovation, but to build an unyielding perimeter around retail capital. While institutions can access sophisticated derivatives, retail players are strictly restricted to spot markets.”
The regulator has also mandated that all licensed entities hold customer assets in an independent, trust-backed custody structure. This ensures that even if an exchange faces severe operational insolvency or a sudden liquidity squeeze, user funds are structurally segregated from the platform’s corporate balance sheet, drastically reducing the risk of a total capital loss.
The Risk Reality Check
Despite these comprehensive regulatory layers, authorities continue to issue stark warnings regarding the baseline risks of the digital asset market. Cryptocurrencies remain completely excluded from Singapore’s Deposit Insurance Scheme (DIS), which guarantees standard bank deposits up to S$100,000.
Market experts emphasize that if a digital token loses its underlying value, or if a platform suffers a catastrophic exploit, there is no state-backed safety net to make retail investors whole. This reality has triggered a parallel cultural shift toward self-custody. An increasing percentage of local Ethereum and Bitcoin buyers are choosing to bypass exchange wallets entirely, electing to migrate their digital property into private hardware storage.
Looking Ahead
As Singapore navigates this period of high adoption and tightening oversight, the market is entering a phase of mature, institutionalized growth. The combination of instant domestic payment options like PayNow and a transparent, albeit uncompromising, regulatory framework has weeded out bad actors while providing a secure playground for legitimate market participants.
For global Web3 entities, Singapore’s regulatory model represents a blueprint for sustainable development. For local retail investors, the message remains clear: the infrastructure to acquire digital assets has never been more secure or accessible, but the ultimate responsibility for risk management rests entirely in their own hands.